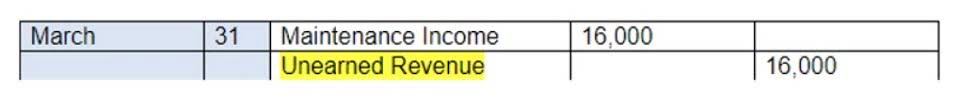
So for example a debit entry to an asset account will increase the asset balance, and a credit entry to a liability account will increase the liability. An abnormal balance can indicate an accounting or payment error; cash on hand should never have a net credit balance, since one cannot credit (pay from) cash what has not been debited (paid in). Similarly, there is little reason for a business to pay a liability in excess of what it owes. On the other hand, a business that has not reached profitability will debit a cumulative earnings/loss equity account with its losses, resulting in a negative balance.
Let’s Walkthrough Some Examples on Normal Balances of Accounts
In budgeting and forecasting, normal balances serve as a guide for predicting future financial transactions and their impact on a company’s financial statements. When creating a budget, accountants project the expected debits and credits for each account, based on historical https://www.bookstime.com/ data and anticipated business activities. This projection helps in setting financial targets and establishing benchmarks for performance evaluation. Revenue accounts track the income a company earns from its normal business operations, such as sales of goods or services.
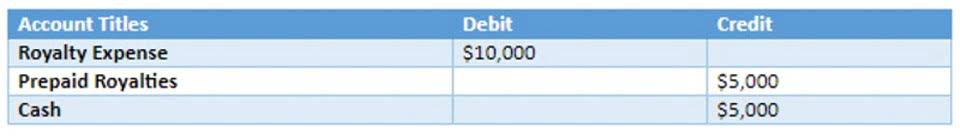
Examples of Debits and Credits in a Sole Proprietorship
The accounting equation emphasizes a basic idea in business; that is, businesses need assets in order to operate. First, it can sell shares of its stock to the public to raise money to purchase the assets, or it can normal balance of accounts use profits earned by the business to finance its activities. Second, it can borrow the money from a lender such as a financial institution. You will learn about other assets as you progress through the book.
What are Closing Entries in Accounting? Accounting Student Guide
Cash activities are a large part of any business, and the flow of cash in and out of the company is reported on the statement of cash flows. Recall that the basic components of even the simplest accounting system are accounts and a general ledger. Accounts shows all the changes made to assets, liabilities, and equity—the three main categories in the accounting equation. Each of these categories, in turn, includes many individual accounts, all of which a company maintains in its general ledger.
Residual Value Impact on Asset Depreciation and Finance
- Notes receivable is similar to accounts receivable in that it is money owed to the company by a customer or other entity.
- This type of chart lists all of the important accounts in a company, along with their normal balance.
- By applying the principles of normal balance, businesses can maintain balance in their financial records and present transparent and meaningful financial information to stakeholders.
- Salaries Expense will usually be an operating expense (as opposed to a nonoperating expense).
- If the payment was made on June 1 for a future month (for example, July) the debit would go to the asset account Prepaid Rent.
A notes payable is similar to accounts payable in that the company owes money and has not yet paid. Some key differences are that the contract terms are usually longer than one accounting period, interest is included, and there is typically a more formalized contract that dictates the terms of the transaction. Forecasting, on the other hand, uses normal balances to estimate the financial outcomes of various scenarios. By applying expected transactions to the normal balances of accounts, financial professionals can simulate the effects of business decisions on the company’s financial trajectory. This forward-looking approach is instrumental in strategic planning and risk management, as it allows businesses to prepare for potential financial challenges and opportunities.


